Meta description: Discover how AI-powered job costing can reveal labor overruns, material waste, pricing gaps, and other hidden profitability problems in sign and graphics businesses.
A sign company can look busy, maintain a healthy sales pipeline, and even report growing revenue while still losing money on certain types of work. That is one of the most dangerous realities in custom manufacturing: activity is not the same as profitability.
The problem is rarely a single, dramatic mistake. More often, profit disappears a little at a time. An estimator overlooks a finishing step. A fabrication team uses more material than expected. Installation takes an extra day. A project manager spends hours coordinating revisions that were never included in the quote. Freight costs increase, but pricing does not. Each variance may seem small on its own, yet together they can turn an apparently successful job into a disappointing result.
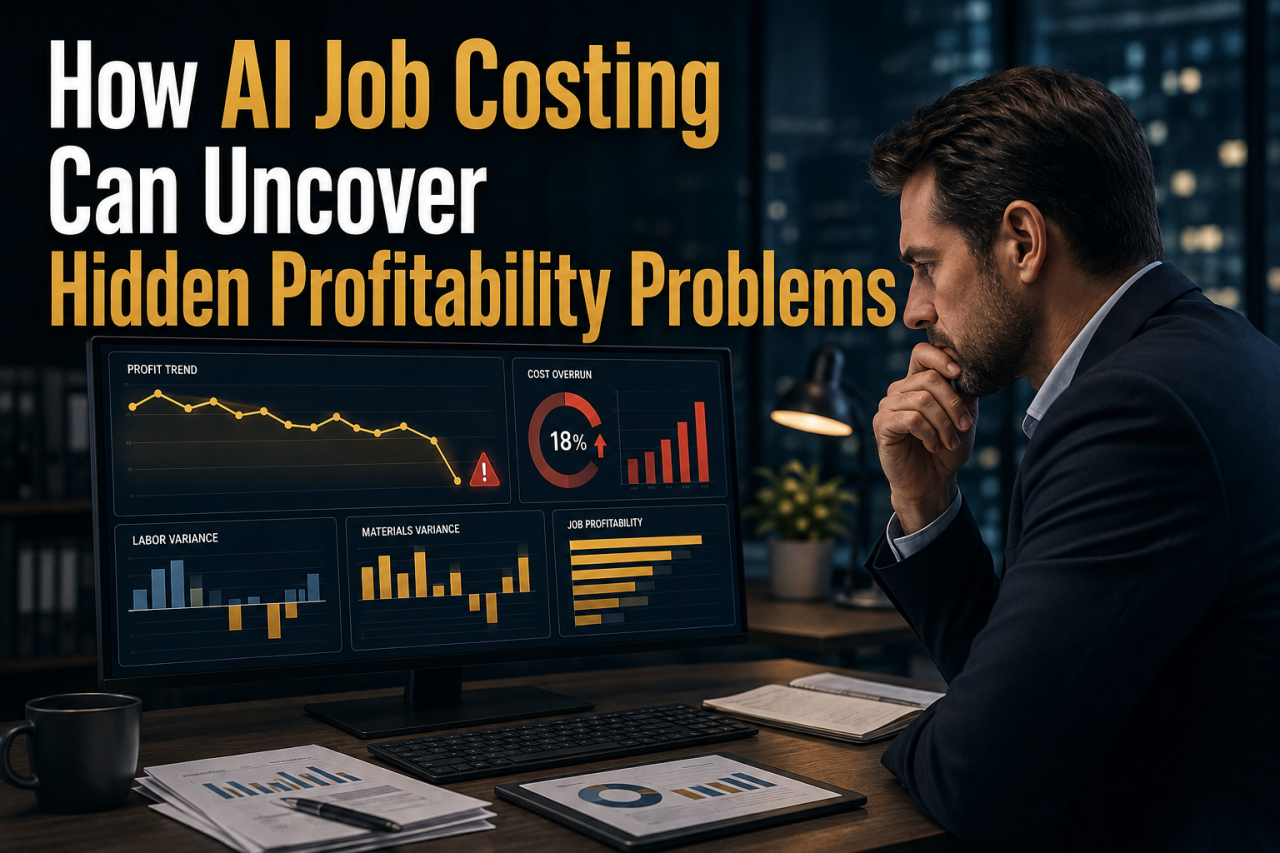
Traditional job costing can reveal these issues after someone assembles and reviews the numbers. AI-enhanced job costing has the potential to go further. By analyzing estimates, labor entries, material usage, purchasing, production activity, change orders, and completed-job results, AI can help identify patterns that people may miss. Instead of only answering, “Did this job make money?” it can help answer, “Why did the margin change, where is the same problem happening again, and which active jobs may be at risk next?”
For sign and graphics companies that handle custom projects, multiple departments, outside services, and field installation, that added visibility can make a meaningful difference.
Why Profitability Problems Are So Easy to Miss
Most businesses know their overall revenue and expenses. Many also review gross profit at the end of the month. Those figures are important, but they do not always explain what is happening inside individual jobs.
A company may have strong total revenue because profitable projects are offsetting poor ones. A high-volume customer may also require so many revisions, rush orders, special deliveries, and administrative touches that the relationship is less profitable than it looks.
Job-level profitability becomes especially difficult to understand when information is scattered among estimating software, spreadsheets, timecards, purchasing records, inventory systems, emails, and accounting software. By the time the data is combined, the job is closed and the next several projects are already underway.
That delay creates a management problem. Teams cannot correct an overrun they cannot see, and estimators cannot improve future pricing when the true causes of past losses remain hidden.
What AI Adds to Job Costing
Conventional job costing compares revenue with direct materials, labor, subcontracting, and allocated overhead. It provides the financial structure needed to evaluate a project. AI does not replace that structure; it makes the available data easier to analyze at scale.
When supported by reliable operational data, AI can examine many jobs and look for relationships among variables such as job type, customer, material, department, crew, turnaround time, revision count, and final margin.
This can help management move beyond isolated job reviews. For example, one installation overrun might seem unusual. But if projects involving a particular sign type, geographic area, or permitting condition repeatedly exceed planned installation hours, the pattern deserves attention. AI can surface that pattern faster than a manager manually reviewing job reports one by one.
AI can also establish normal ranges. If similar channel-letter projects typically use 42 to 48 fabrication hours, a new job trending toward 65 hours can be flagged before completion. The value is not simply that the system calculates a variance. The value is that it can recognize which variances are unusual, recurring, or likely to affect the outcome.
Hidden Problem No. 1: Labor That Was Never Fully Costed
Labor is one of the most common sources of margin erosion. It is also easy to undercount.
Estimates may include production and installation time while overlooking project management, file preparation, proofing, purchasing, packaging, travel, site coordination, equipment setup, rework, and cleanup. Employees may also enter time late or assign it to a general category rather than the correct job.
AI analysis can compare estimated and actual labor across departments and project types. It may reveal that certain products regularly require more design time, that one installation category consistently needs a second crew member, or that rush jobs generate additional administrative work not reflected in the selling price.
The business can then adjust labor standards, improve time-entry practices, change workflows, provide training, or increase prices. Without detailed analysis, management may only see that labor was high without understanding why.
Hidden Problem No. 2: Material Waste and Cost Creep
Material overruns do not always appear as obvious waste. They may come from spoilage, remakes, inaccurate yields, substitutions, minimum purchase quantities, color matching, damaged inventory, outdated costs, or small items that never make it onto the estimate.
In a sign operation, the difference between planned and actual consumption can accumulate quickly across aluminum, acrylic, vinyl, LEDs, power supplies, paint, hardware, packaging, and other materials. Vendor price increases can create another gap when estimating tables are not updated promptly.
AI can help compare bill-of-material expectations with actual material usage and purchasing data. It can identify products with recurring consumption variances, materials whose costs are rising faster than selling prices, and jobs that repeatedly require remakes or substitutions.
It can also separate exceptions from systematic problems. Repeated excess substrate use on the same product family may indicate an inaccurate formula, inefficient nesting, poor handling, or a production standard that needs revision.
Hidden Problem No. 3: Profitable Sales That Become Unprofitable Jobs
An estimate represents what the company expects to happen. Production records show what actually happened. The space between those two versions of the job is where profitability problems often hide.
A quote may be financially sound when approved, but the scope can gradually expand. The customer requests additional proofs. Site conditions require extra work. Specifications change without a formal change order. The schedule is compressed. A vendor delay leads to expedited freight. The company absorbs these costs to keep the project moving.
AI can analyze the differences between quoted assumptions and actual job activity. It may find that jobs with multiple revisions have lower margins, that orders with short lead times generate more overtime, or that projects for a particular customer frequently include unbilled additions.
These findings are a reason to price and manage the work more accurately. The company might add revision limits, rush fees, site-condition allowances, minimum charges, or clearer change-order requirements.
Hidden Problem No. 4: Customers and Products With Misleading Margins
Revenue reports often highlight the largest customers and best-selling products. Job-cost data may tell a different story.
A high-volume customer may negotiate aggressive pricing, demand fast turnarounds, submit incomplete artwork, or require special billing and delivery procedures. A popular product may appear profitable based on standard costs but perform poorly after setup time, scrap, support, and installation complexity are included.
AI can group completed jobs by customer, product family, sales representative, industry, location, or other meaningful categories. It can then compare revenue, gross margin, labor variance, material variance, cycle time, and frequency of exceptions.
The analysis may reveal that a smaller customer is more profitable than a larger one or that a common product needs to be redesigned, standardized, or repriced. Decisions can then reflect economic performance rather than sales volume alone.
Hidden Problem No. 5: Operational Bottlenecks That Look Like Cost Problems
Not every margin problem begins with pricing. Sometimes the underlying cause is operational.
Jobs may wait for approvals, materials, equipment, information, or scheduling decisions. Employees may switch repeatedly between tasks. A bottleneck in one department can cause overtime in another. Work may be produced before final specifications are confirmed, creating avoidable remakes.
AI can examine timestamps, workflow stages, labor entries, and production events to identify where jobs slow down or depart from the normal process. If low-margin jobs regularly spend extra time in prepress, pause before installation, or return to fabrication after quality review, those patterns can point toward the true source of the cost.
Better job-cost intelligence helps leaders determine whether they have a pricing, planning, training, or capacity issue. Raising prices may cover an inefficient process, but it does not fix that process.
From Historical Reporting to Early Warning
One of the biggest opportunities for AI job costing is the shift from retrospective reporting to proactive management.
Traditional completed-job reviews are useful, but they arrive after the money has been spent. AI models can use the progress of active jobs to estimate where final costs and margins may land. If labor usage is already high relative to the percentage of work completed, or material consumption is outside the normal range, managers can receive an early warning.
That warning might prompt a manager to verify the scope, approve a change order, investigate a remake, or communicate with the customer. Not every alert requires intervention, but earlier visibility creates more choices.
Predictive insights should be treated as decision support, not unquestionable answers. Forecasts are only as reliable as their data and assumptions. The best results come when AI highlights a potential issue and a knowledgeable employee evaluates the context.
The Data Foundation Comes First
AI cannot repair incomplete job-cost records by itself. If employees do not record labor, material usage is inconsistent, change orders are missing, or cost tables are outdated, the analysis will reflect those weaknesses.
Before expecting advanced insights, businesses should establish a consistent job-costing foundation. At minimum, that means:
- Creating realistic labor and material budgets during estimating
- Maintaining accurate labor rates, material costs, and overhead assumptions
- Recording time against the correct jobs and departments
- Tracking actual material consumption and purchased items
- Capturing subcontractor, freight, equipment, and other direct costs
- Documenting scope changes and approved change orders
- Closing jobs consistently so results can be compared
- Using standardized product, customer, and job classifications
The goal is reliable, consistent data that improves over time. AI can also flag data-quality anomalies, such as missing time entries or costs posted after a job closes.
Questions AI-Enhanced Job Costing Can Help Answer
The most effective implementations begin with business questions rather than technology. Leaders might ask:
- Which job types most often miss their estimated margins?
- Where do actual labor hours consistently exceed the budget?
- Which materials create the largest unfavorable variances?
- Are rush orders truly profitable after overtime and expedited freight?
- Which customers generate the most unbilled work?
- Which estimators produce the most accurate cost projections?
- At what point in the workflow do low-margin jobs begin to deviate?
- Which active projects are most likely to finish below target margin?
- What estimate assumptions should be updated based on completed jobs?
Clear questions determine which data, alerts, and reports will be useful—and help turn information into action.
Turning Insights Into Higher Margins
Finding a profitability problem is only the first step. The value comes from incorporating the lesson into daily operations.
If analysis shows that a product routinely exceeds its labor budget, the company should update the estimating standard, investigate the workflow, or both. If a customer’s projects require frequent revisions, the sales team can clarify what is included and establish fees for additional work. If a material produces high scrap, purchasing and production can evaluate alternatives, handling practices, or order quantities.
Ownership also matters. Estimating may own labor standards, purchasing may own vendor costs, production may own material usage, and project management may own change-order compliance. Reviews should focus on meaningful exceptions and corrective actions.
Over time, this creates a feedback loop: actual job results improve future estimates; better estimates set more realistic budgets; active-job monitoring catches deviations earlier; and completed-job analysis reveals whether the corrective changes worked.
How an Integrated Platform Supports Better Job Costing
AI analysis becomes more useful when sales, estimating, production, inventory, purchasing, labor, and financial activity are connected. Separate spreadsheets and applications force teams to spend more time reconciling records and less time interpreting results.
Mothernode provides sign companies with an integrated platform for managing processes from sales and estimating through production and financial activity. Its job-costing workflows can compare budgeted and actual materials and labor when detailed production budgets are established, helping businesses evaluate variances, waste, overruns, bottlenecks, and project profitability.
That connected operational foundation is essential for any company preparing to use AI responsibly. The stronger and more complete the underlying job data, the more meaningful AI-assisted analysis can become. Instead of relying on disconnected snapshots, leaders gain a clearer path from the original estimate to the final result.
A Clearer View of What Really Drives Profit
Hidden profitability problems thrive in disconnected systems, inconsistent tracking, and delayed reporting. They remain hidden when a business knows how much it sold but not precisely what each job required to deliver.
AI-enhanced job costing can help change that. It can identify recurring labor overruns, material variances, unpriced scope, unprofitable customer behaviors, operational bottlenecks, and active jobs that may be heading off budget. Just as importantly, it can help companies recognize their most profitable work and repeat it more intentionally.
The objective is not to replace estimators, project managers, production leaders, or financial professionals. It is to give them earlier, clearer, and more focused information. When experienced people can see the full story behind every job, they can price with greater confidence, improve processes, address problems sooner, and protect margins as the business grows.
For sign and graphics companies, that is the real promise of AI job costing: not simply more data, but a better understanding of where profit is created, where it is leaking away, and what to do next.